If I had a dollar for every time someone asked me, "Stephen, should I just wait until rates drop back to 3%?"... I would be writing this from a beach somewhere.
It is the number one question I hear in real estate right now. So let me give you the honest answer, with the actual numbers behind it.
What do the numbers actually look like?
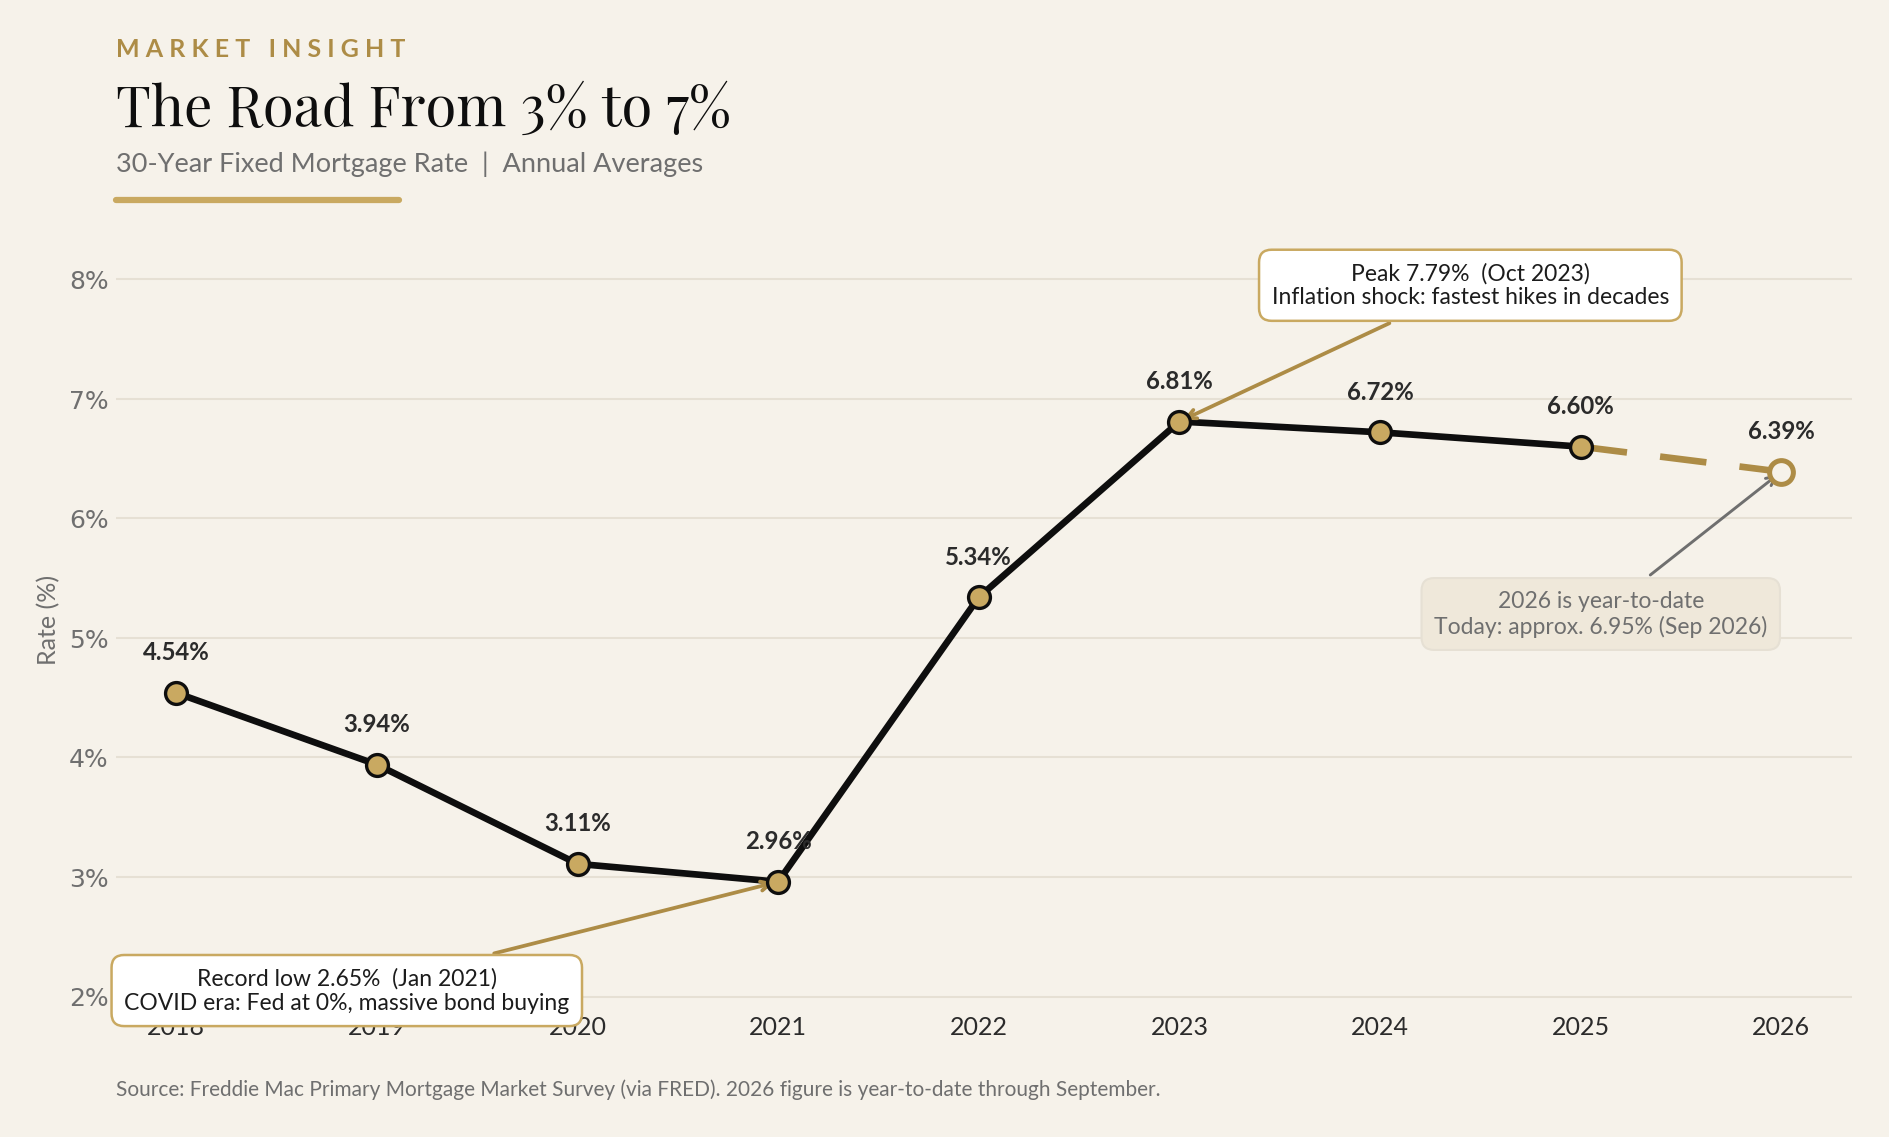
Annual average 30-year fixed mortgage rates, per Freddie Mac:
- 2018: 4.54%
- 2019: 3.94%
- 2020: 3.11%
- 2021: 2.96%
- 2022: 5.34%
- 2023: 6.81%
- 2024: 6.72%
- 2025: 6.60%
- 2026 year-to-date: about 6.39%
The record low was 2.65% in January 2021. The cycle peak was 7.79% in late 2023. Today we are sitting around 6.95%.
How did we get 3% mortgage rates in the first place?
Those 3% rates were not normal. They were emergency rates.
When COVID hit in March 2020, the Federal Reserve cut its benchmark rate to zero and bought trillions in bonds to keep the economy alive. The average 30-year fixed mortgage rate fell to 3.11% in 2020 and 2.96% in 2021, bottoming at 2.65% in January 2021, the lowest ever recorded.
Here is the part nobody likes to hear: 3% mortgage rates came with a global pandemic attached.
How did we end up near 7%?
Then inflation took off. It hit 9.1% in June 2022, the highest in 40 years. The Fed responded with the fastest round of rate hikes in decades, and mortgage rates followed. They crossed 7% in October 2022 and peaked at 7.79% in late 2023.
Since then we have been living in the 6s. Rates opened 2026 at 6.06%, climbed in the spring, and after the Fed's September rate hike we are sitting around 6.95% as of this month.
So will mortgage rates go down to 3% again?
Honestly? Not without another major crisis. For rates to return to 3%, the economy would need the kind of emergency that forces the Fed back to zero, and that is not a tradeoff anyone should want.
Mortgage rates follow the 10-year Treasury yield, plus a spread on top. For your mortgage rate to hit 3%, that yield would need to fall from over 5% today to around 2.25%. That only happens if the Fed cuts rates back toward zero and restarts large bond buying, which only happens when the economy is in deep trouble.
One economist put it well: 3% rates would come at a steep cost, widespread economic pain. You do not actually want the thing that causes 3% rates.
What are the mortgage rate predictions for 2027 and 2028?
The major forecasters are all in the same neighborhood, the mid to high 6s:
- Fannie Mae: 6.8% late this year, easing to 6.7% in 2027
- Mortgage Bankers Association: around 6.5% straight through 2028
- Wells Fargo: 6.4%, drifting toward 6.3%
Nobody, and I mean nobody, is forecasting a return to 3%, 4%, or even 5%. The new normal is 6 to 7%.
What does this mean if you are thinking about buying?
If you are waiting for 3% to buy, you might be waiting for the next crisis to get it, and competing with everyone else who waited. If you hold a mortgage from 2020 or 2021 at 3 percent, the rate you give up is now as much a cost of moving as the price you get, something I covered in The Most Expensive Mortgage in America Is the One You Already Have.
Here is what I tell my buyers: buy the home, not the rate. Seller-paid rate buydowns, adjustable rate options, and negotiating on price are real tools working right now. And when rates ease down the road, you refinance.
For sellers, the same math cuts both ways. Buyers have made peace with the 6s, which means well-presented homes are still moving, but the era of buyers stretching on price because the rate made it work is over. Pricing precision matters more now than it has in years.
If you are weighing a purchase or a sale anywhere from Beverly Hills to Malibu to Calabasas, start with the facts about your own home. Get an instant estimate of what your home is worth, read the Seller's Playbook for how to prepare, and then reach out to me directly. I will walk you through the real numbers, not the headlines.